
The short answer
FP&A consulting delivers the planning and reporting a company needs to make decisions with numbers instead of instinct: a budget built from drivers, a rolling forecast that shows cash ahead of time, a monthly package that explains what changed and why, a short set of measures the leadership team runs the business on, and the analysis behind the decisions in between, from hiring to pricing to a loan. For a $5M to $50M company it fills the gap between bookkeeping, which records what happened, and a CFO, who decides what to do about it.
"FP&A" stands for financial planning and analysis, and the name does not help an owner who is trying to work out what they would get for the money. Bookkeepers and accountants record the past and keep the business compliant. Strategy advisors talk about the future. FP&A is the work in between: turning the company's own numbers into a forward view and using it to test decisions before they are made. Large companies have a department for it. A $5M to $50M company usually has a spreadsheet and the owner's memory.
This guide lists what an FP&A engagement delivers, in the order it is built, shows one decision worked through the way FP&A would work it, explains the monthly rhythm that keeps the work alive, and covers when a company needs it, what it does not do, and how to judge whether it is working. If you are comparing providers, our guide to comparing fractional CFO firms covers the selection questions.
Where FP&A sits
| Bookkeeping and accounting | FP&A | Fractional CFO | |
|---|---|---|---|
| Looks | Backward: what happened | Forward: what will happen, and what if | Outward: bank, investors, buyers, the board |
| Produces | Closed books, statements, tax filings | Budget, forecast, monthly package, measures, decision analysis | Capital strategy, lender and investor relationships, the decisions themselves |
| Answers | How much did we make last month? | What happens to cash if we hire three people in March? | Should we, and how do we fund it? |
| Rhythm | Monthly close | Monthly cycle after the close, with the budget once a year | A few hours a month, more around events |
The three depend on each other. FP&A is built on a close that lands on time, and a CFO's decisions are only as good as the analysis beneath them. Our post on the difference between strategic finance, a fractional CFO and bookkeeping draws the lines in more detail.
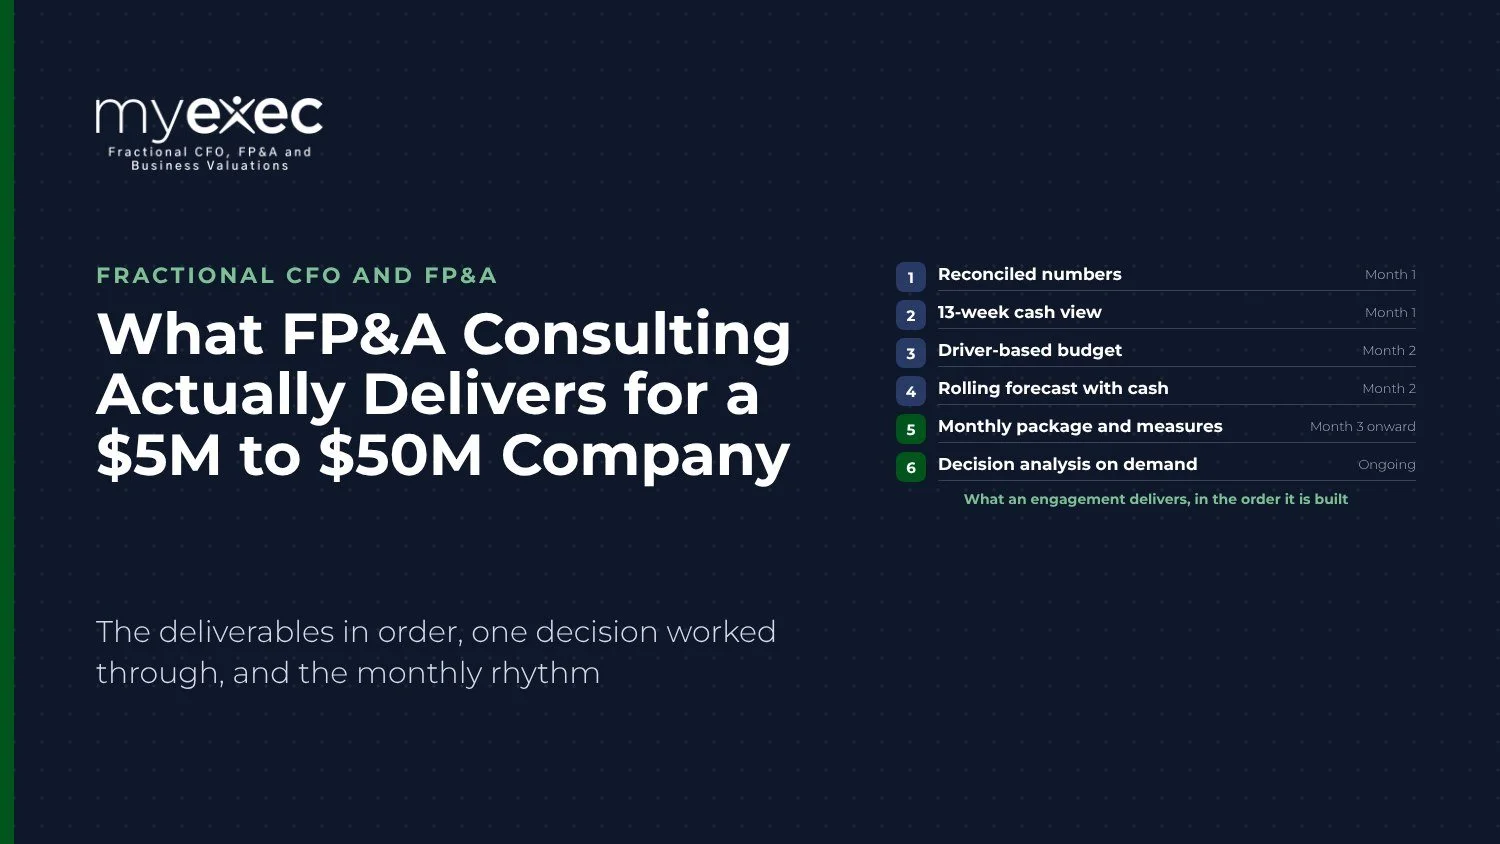
What an engagement delivers, in the order it is built
- A reconciled baseline. One set of numbers everyone trusts: the books tied to the bank, revenue by customer and product, costs by driver, and a chart of accounts that supports management reporting rather than just the tax return. Until this exists, every meeting is an argument about whose figures are right.
- A 13-week cash view. Collections and payments week by week for the next quarter. It is the first forward view most owner-led companies have had, and it usually changes a decision within the first month. Our guide to the cash flow forecasting process covers how it is built.
- A driver-based budget. Revenue stated as volume times price by line, costs tied to the drivers that cause them, headcount by role and start date. Built once a year, and built so that a miss can be traced to a driver. Our guide to business budgeting covers the process.
- A rolling forecast with cash. The income statement, balance sheet and cash flow projected twelve or thirteen months ahead, rolled every month with actuals, so the view never shortens and the covenants and the cash low point are visible months out. Our post on rolling forecasts and budgets explains how the two work together.
- The monthly package. Actuals against budget and forecast, the variances that matter explained by driver, the measures, and a short forward note, delivered on a date relative to month end. Our guide to improving financial reporting covers what goes in it.
- A short set of measures. Five to eight numbers the leadership team runs the business on, chosen for this business, with a monthly meeting to review them. Our post on business performance metrics covers how to choose them.
- Decision analysis on demand. The hire, the price change, the new location, the equipment purchase, the customer contract, each modeled against the forecast before it is signed. This is the part owners value most once they have had it, and it is the part the example below shows.
- Lender, board and buyer packages. The same numbers presented for an outside reader: a bank renewal, a board meeting, a quality of earnings review. Our post on what banks look for covers the first of those.
Items 1 through 4 are usually built in the first 90 days; items 5 and 6 start in the second or third month and run from then on; items 7 and 8 come as the business needs them. A company that already has some of the list, such as a strong controller who closes on time, starts further along.
A worked example: the hiring decision
The figures are hypothetical and rounded. A $12M services company wants to add three salespeople. The owner's reasoning is quick: each one should bring in $600,000 a year, so that is $1.8M of revenue for about $540,000 of fully loaded cost. FP&A asks three more questions: what is the gross margin on the revenue they bring, how long does a new hire take to reach full productivity, and what happens to cash in the meantime?
With a 35% gross margin and a six-month ramp, the answers change the decision. The three hires produce $630,000 of gross profit a year at full productivity against $540,000 of cost, a contribution of $90,000 a year once they are up to speed. Before that, the company funds them: cash is about $94,000 behind at month five, and the hires do not pay back their cost until month 18. If each one brings in $500,000 instead of $600,000, they never pay back at all.
None of this says the hires are wrong. It says the decision is about margin per hire and ramp time rather than headcount, that the company needs about $100,000 of cash headroom to make it, and that the hires should come with a plan for the margin, such as pricing or a product mix, and a 90-day productivity check. That is what FP&A delivers: the question reframed, the cash consequence seen in advance, and a way to tell within a quarter whether the plan is working. Test your own hire below.
Hiring decision check
Enter the figures to see the cash investment, the payback month and the yearly contribution.
In an engagement this analysis sits inside the rolling forecast, so the cash dip shows up against the credit line and the covenants rather than on its own. Our strategic finance guide covers the seven tools the forecast is built from.
The monthly rhythm
The deliverables only matter if they are used every month, and the engagement is organized around the close. In the week after the books close: actuals loaded, variances explained by driver, forecast rolled, package out. In the following week: the leadership meeting on the measures and the forward view, with one decision on the agenda. Through the month: the decision analyses as they come up, and the work on whatever the package showed. In our engagements the package carries a date relative to month end, and the first question at the review is whether last month's actions happened.
When a company needs it
The usual triggers are practical: a line of credit renewal or a loan request that needs a forecast, cash that is tight even though the business is profitable, a budget season that produced a single revenue line nobody can explain a variance against, a pricing or hiring decision too large to make on instinct, a margin that has slipped for two quarters without anyone saying why, or a sale or capital raise one to three years out that will need numbers a buyer can test. Companies also arrive at FP&A when the owner realizes that every financial question in the business comes back to them, which is a sign the finance function has not grown with the company.
Two things FP&A does not do. It does not replace the bookkeeper or the CPA; it builds on a close that lands on time and leaves tax to the people who do tax. And it does not make the decisions. It puts the numbers in front of the owner, or the CFO, in time to make them well.
How to tell whether it is working
- The package arrives on its date, every month, with the forecast rolled.
- The forecast is close three months out on revenue, margin and cash, and gets closer as the drivers are tuned.
- The leadership meeting has a forward agenda, and last month's actions are checked at the start of it.
- Decisions come with a page of numbers, and the owner can say what would have to be true for the decision to work.
- The cash surprises stop, because the low point was visible months ahead.
- The bank and the board ask fewer questions, because the package answered them.
Within six months most of these are visible or they are not. In our FP&A work the 90-day review against the original scope is where the owner and the team decide what to add, what to drop and whether the rhythm is holding.
Common mistakes
- Starting FP&A on a late close. A forecast built on books that land on the 25th is wrong before it is read. Fix the close first.
- Buying reports instead of decisions. A package nobody acts on is overhead. The review meeting is the product.
- Too many measures. Thirty numbers on a dashboard means none of them get watched.
- A budget with one revenue line. If price and volume were never stated, no variance can be explained.
- Skipping the cash view. Profit forecasts without the balance sheet miss the thing owners worry about most.
- Treating it as a project. The models are the easy part. The monthly rhythm is what changes the business, and it has to be run.
Frequently asked questions
What does FP&A consulting deliver?
A reconciled set of numbers, a 13-week cash view, a driver-based budget, a rolling forecast with cash, a monthly package that explains variances by driver, a short set of measures with a review meeting, analysis of individual decisions such as hires and pricing, and packages for lenders, boards and buyers. The first four are built in the first 90 days; the rest run monthly from then on.
How is FP&A different from accounting or a fractional CFO?
Accounting records what happened and keeps the company compliant; FP&A projects what will happen and tests decisions against the projection; a fractional CFO makes the capital, banking and strategic decisions and represents the company to lenders, investors and buyers. The three depend on each other, and many engagements combine FP&A with a CFO-level lead so the analysis and the decisions come from one team.
When should a $5M to $50M company bring in FP&A?
When a decision is too large to make on instinct, when cash is tight despite profit, when a lender or investor asks for a forecast, when the budget cannot explain its own variances, when margin has slipped without a clear cause, or one to three years before a sale. The common thread: the owner is the only person who can answer a financial question, and the questions have outgrown that.
What does the first 90 days look like?
The first month reconciles the numbers, builds the 13-week cash view and agrees the measures. The second builds the budget or forecast from drivers and delivers the first monthly package. The third runs the full rhythm: close, package, review, decisions, with the forecast rolled once on actuals and a review against the original scope. A company with a strong controller starts further along.
Do I need new software for FP&A?
Usually not at first. A reliable close, a well-built spreadsheet model and a disciplined monthly rhythm are enough for most $5M to $50M companies. Reporting tools earn their place once the number of locations, products or entities makes the spreadsheet slow or fragile, or once several people need the same numbers at the same time. The rhythm matters more than the tool.
How do I know whether FP&A is working?
The package arrives on its date every month with the forecast rolled; the three-month forecast is close on revenue, margin and cash; the leadership meeting has a forward agenda and checks last month's actions; decisions come with a page of numbers; cash stops surprising anyone; and the bank and board ask fewer questions. Most of these are visible within six months or they are not.
See what the first 90 days would build for your company
MyExec staffs FP&A from analyst through director, with a CFO-level lead when the decisions call for one, tied to your monthly close and scaled to the work. On a free 30-minute call we will walk through your situation and say what we would build first.
Prefer to read first? Download the strategic finance guide, seven tools for building a strategic finance function, or see how the levels fit together on our services page.