Variance Analysis Terms Demystified
Core Categories of Variance Analysis in Financial Reporting
Understanding the financial health of an expanding company requires more than glancing at the bottom line of an income statement. When executive teams evaluate their operating results, they use variance analysis to systematically contrast actual operational outcomes against their initial annual plans or rolling expectations. By isolating why performance differed from baseline targets, finance teams can improve financial reporting and deliver actionable visibility to department heads.
A budget is a quantitative expression of a business plan. Once operations commence, real-world conditions introduce deviations. The primary job of management accounting isn't just recording these deviations, but classifying them into coherent categories so management can determine if operational corrections, pricing adjustments, or strategic shifts are necessary.
Favorable vs. Unfavorable Variances
Every variance falls into one of two fundamental classifications:
- Favorable Variances (F): These occur when actual financial outcomes surpass planned targets, resulting in higher-than-expected net income. Examples include generating more revenue than budgeted, paying lower unit prices for direct raw materials, or operating with fewer direct labor hours than standard benchmarks.
- Unfavorable Variances (U): These occur when financial performance lags the plan, directly reducing net income. Examples include missing revenue milestones, incurring unbudgeted overhead costs, or facing unexpected wage inflation.
A favorable variance isn't always an unmitigated win. If your sales department generates a favorable revenue variance by offering massive volume discounts, the resulting gross margin might suffer. Similarly, an operations team might create a favorable direct materials cost variance by purchasing cheaper raw components, only to trigger massive unfavorable scrap and labor efficiency variances down the line.
Viewing each line item in isolation often obscures the broader picture. Effective cost structure optimization requires examining how line-item variances interact across the entire organization.
Materiality Thresholds and Flexible Budgeting
A common trap for growing middle-market businesses between $5M and $50M in revenue is treating every single budget discrepancy with equal importance. Controller teams can burn hours drafting explanations for a $400 utility bill difference while ignoring a subtle 2% gross margin erosion across a $10M product line.
To avoid this, organizations establish materiality thresholds. These rules define the specific dollar and percentage boundaries that require formal operational investigation. Variances below the threshold are deemed immaterial noise and logged automatically, while variances exceeding the threshold trigger root-cause discovery.
Equally important is distinguishing between static budgets and flexible budgets in ongoing profit and loss management. A static budget remains fixed regardless of actual sales volume. A flexible budget adjusts standard allowable costs based on the actual output volume achieved during the period.
| Evaluation Criteria | Static Budget Analysis | Flexible Budget Analysis |
|---|---|---|
| Volume Sensitivity | Fixed at original baseline expectation | Dynamically scales with actual sales or production volume |
| Cost Benchmarks | Compares actual expenses against baseline plan | Recalculates standard allowable costs for actual activity |
| Managerial Utility | Evaluates high-level goal attainment | Isolates true operational spending and efficiency performance |
When sales volume spikes by 30%, variable costs like direct labor and materials will naturally exceed the static budget. Under a static framework, this looks like poor expense management. Under a flexible budget, it becomes clear whether the team produced that extra 30% volume efficiently or overspent on raw inputs.
The Price-Volume-Mix Breakdown
Topline revenue variances are rarely driven by a single factor. If revenue beats the plan by $500,000, that surplus represents a blend of changes in unit selling prices, overall units sold, and the relative proportion of higher-margin versus lower-margin offerings.
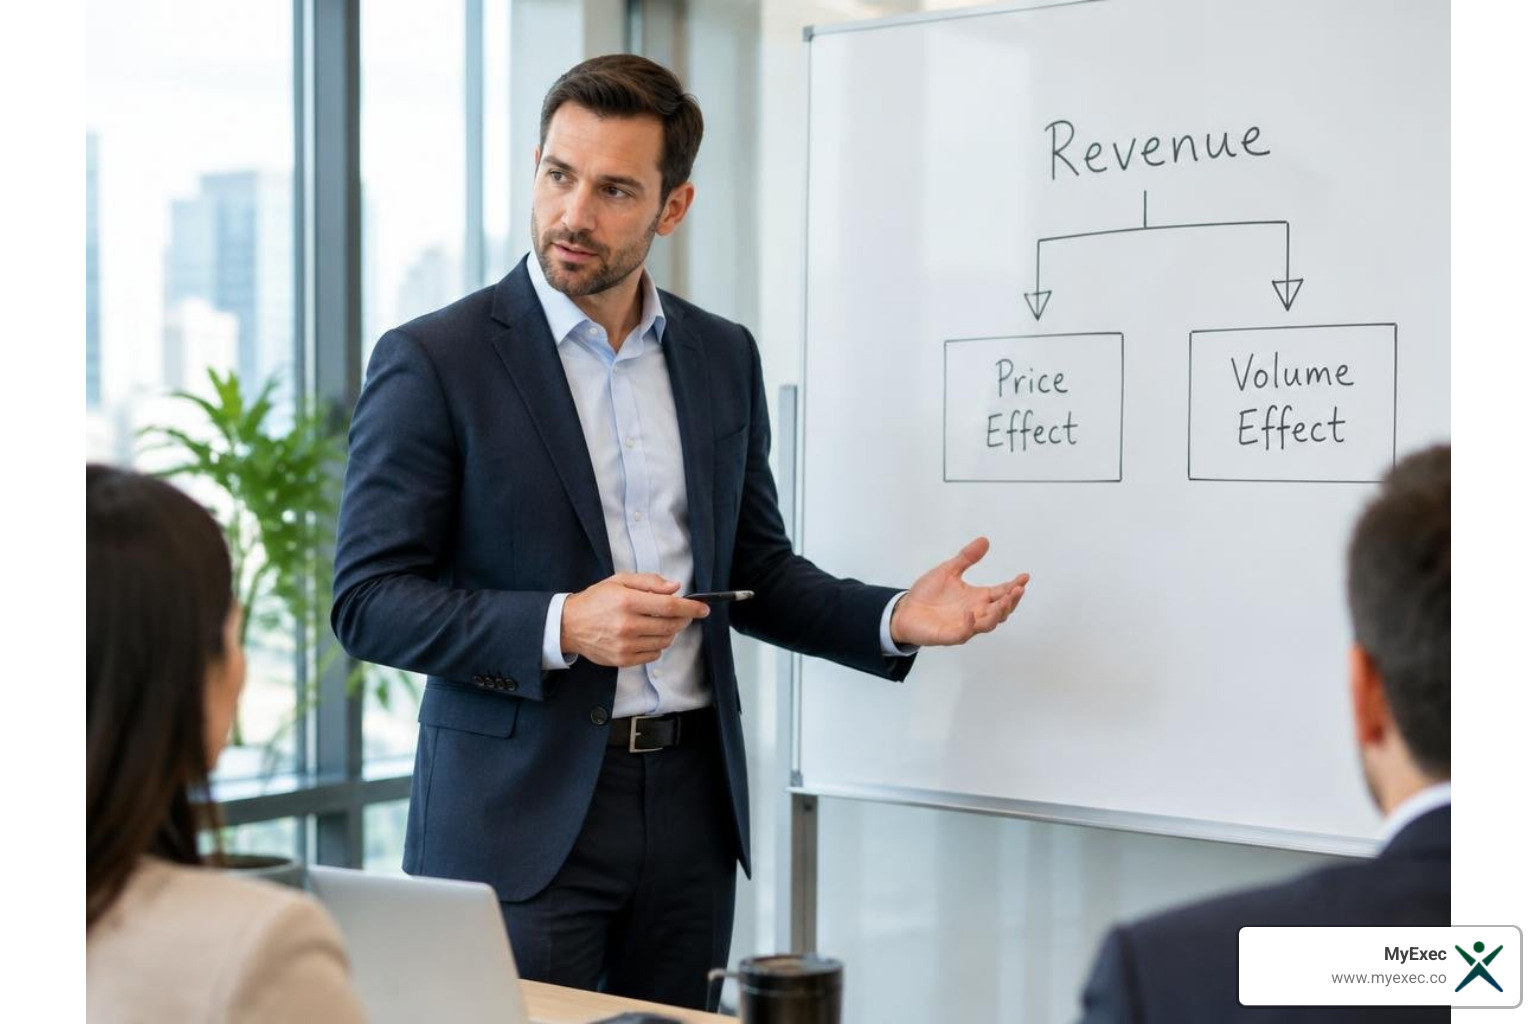
Many mid-sized companies don't perform systematic price-volume-mix decomposition, even though it's a cornerstone of professional financial analysis. Without this breakdown, leadership teams misdiagnose commercial health. Rigorous mathematical and statistical variance decomposition methodologies allow management to unpack multi-variable commercial environments cleanly.
Price and Rate Variances
The price variance measures the portion of a revenue deviation caused solely by changes in unit pricing relative to the standard budgeted price:
- Selling Price Variance = (Actual Unit Price - Budgeted Unit Price) * Actual Units Sold
A negative price variance indicates that discounting, promotional deals, or customer contract concessions reduced your realized average unit price.
On the cost side, the identical mathematical concept applies as a rate variance. A direct labor rate variance or material price variance determines whether you paid more or less per unit of input than planned:
- Material Price Variance = (Actual Unit Cost - Standard Unit Cost) * Actual Quantity Purchased
- Labor Rate Variance = (Actual Hourly Rate - Standard Hourly Rate) * Actual Hours Worked
These calculations isolate external price changes or commercial concession decisions from internal operational throughput.
Volume and Mix Decomposition
When a business sells multiple product lines, assessing sales volume requires isolating pure scale from product composition. Analyzing product profitability shows that selling more units overall isn't always positive if customer demand shifted toward low-margin SKUs.
To understand these shifts, we split total volume effects into two distinct components:
- Sales Volume Variance: Measures the financial impact of selling more or fewer total units, assuming standard budgeted mix and margins:
- Sales Volume Variance = (Actual Total Units Sold - Budgeted Total Units Sold) * Budgeted Average Unit Contribution Margin
- Sales Mix Variance: Measures the financial impact of changes in the proportion of individual products sold relative to the original plan:
- Sales Mix Variance = Actual Total Units Sold * (Actual Mix % - Budgeted Mix %) * Budgeted Unit Contribution Margin
Detailed profitability analysis reveals how these subtle commercial mix shifts alter net cash generation. If a software firm sells 1,000 total contracts as planned, but 80% are basic tier instead of enterprise tier, gross margin will decline despite meeting nominal volume targets.
How to Calculate Budget vs. Actual Discrepancies
Operational variance calculations unpack cost variances across direct materials, direct labor, and manufacturing overhead. These equations evaluate shop-floor productivity, capacity utilization, and supplier efficiency.

Accurate calculations depend on reliable inputs established during the budgeting cycle. When forecasting financial statements, standard engineering cards and production routings set baseline targets for direct inputs.
Key Formulas for Operational Variance Analysis
Operational variances separate the price paid for an input from the physical efficiency with which that input was used.
| Variance Type | Calculation Formula | Primary Business Impact |
|---|---|---|
| Material Quantity Variance | (Actual Quantity Used - Standard Quantity Allowed) * Standard Price | Measures material waste, shrinkage, scrap, and operational yield |
| Labor Efficiency Variance | (Actual Hours Worked - Standard Hours Allowed) * Standard Hourly Rate | Evaluates workforce productivity, machine downtime, and scheduling efficiency |
| Variable Overhead Spending Variance | Actual Variable Overhead - (Actual Hours * Standard Variable Overhead Rate) | Captures price fluctuations in consumable supplies, indirect utility rates, and maintenance |
| Fixed Overhead Volume Variance | Budgeted Fixed Overhead - (Actual Output Units * Standard Fixed Overhead Rate) | Highlights production capacity utilization and fixed cost absorption |
Isolating Controllable vs. Uncontrollable Drivers
When an unfavorable cost variance surfaces, leadership must diagnose whether the underlying cause was internal or external before deciding how to respond.
- Controllable Factors: Variables within the operational authority of company management. These include production scheduling, avoidable material scrap, labor overtime approvals, pricing discount thresholds, and standard equipment maintenance.
- Uncontrollable Factors: External macroeconomic shifts outside management's immediate control. These include geopolitical supply chain disruptions, commodity market price swings, regulatory tax changes, and sudden utility tariff increases.
Distinguishing between these categories prevents penalizing operational teams for macroeconomic headwinds while ensuring internal inefficiencies are addressed. Performing scenario vs sensitivity analysis helps finance teams stress-test which operational levers are truly controllable under shifting market conditions.
Turning Variance Reports into Strategic Action
Surveys from the Association for Financial Professionals (AFP) show mid-market FP&A functions rate budget variance reporting as one of their most time-consuming processes, yet one of the lowest in perceived executive value. This disconnect happens when variance reports become static numerical data dumps rather than catalysts for operational decisions.
High-performing finance teams convert numbers into operational course corrections by aligning analysis with concrete business performance metrics.
Executing a Multi-Step Variance Analysis Framework
To make monthly reporting actionable, finance teams can implement a structured five-step drill-down process:
- Detect: Run top-level budget-to-actual comparisons for revenue, gross margin, and operating expenses. Filter out entries below established materiality thresholds to isolate significant deviations.
- Decompose: Break down top-level deviations into core mathematical drivers: price, volume, mix, input rate, and operational efficiency.
- Diagnose: Partner with front-line operational leaders to identify the root cause of each material driver. Determine whether the deviation is a one-off anomaly or a recurring trend.
- Decide: Classify the variance as controllable or uncontrollable, establish an operational remediation plan, and assign a single business owner to execute it.
- Document: Maintain an audit trail of identified drivers, corrective actions, and timeline commitments. Review these commitments in subsequent monthly financial reviews to verify accountability.
Tools, Automation, and Stakeholder Reporting
Manual spreadsheet reporting often limits FP&A teams to historical documentation rather than forward-looking strategy. When financial analysts spend much of their time manually consolidating CSV files and checking formulas, variance commentary is often rushed or shallow.
Modern enterprise resource planning (ERP) platforms and modern business intelligence dashboards allow companies to automate data consolidation. A dedicated financial reporting dashboard enables interactive filtering across product lines, business units, and customer tiers.
Automating data collection lets finance professionals dedicate their time to narrative reporting. An executive-ready variance commentary should answer three questions in plain language:
- What specific driver caused the financial gap?
- What is the projected cash and bottom-line impact over the next two quarters if unaddressed?
- What exact operational step is being taken, who owns it, and when will results normalize?
Frequently Asked Questions About Financial Variances
What is the difference between static and flexible budget variances?
A static budget variance compares actual performance directly against the original, unchanging budget established before the fiscal year began. It measures whether the company hit its absolute top-level financial targets.
A flexible budget variance recalculates the budget using standard cost metrics applied to the actual volume of units sold or produced during the period. It isolates operational efficiency and pricing performance by removing the distorting effects of volume fluctuations.
How do businesses establish meaningful materiality thresholds?
Businesses establish materiality thresholds by combining an absolute dollar amount with a relative percentage change. For example, a mid-market company with $25M in revenue might set a threshold requiring investigation only for line-item variances that exceed both $15,000 and 5% of the budgeted line value.
Tiered thresholds also prevent operational clutter:
- Operational Thresholds (Low): Applied by plant and sales managers to monitor granular weekly consumption and pricing trends.
- Executive Management Thresholds (Medium): Applied during monthly FP&A reviews to evaluate broad business unit performance.
- Board Level Thresholds (High): Reserved for quarterly governance presentations focusing on strategic shifts and enterprise valuation drivers.
Why is price-volume-mix decomposition critical for revenue analysis?
Relying entirely on aggregate revenue figures obscures commercial performance drivers. A business can report revenue growth while experiencing operational degradation if top-line gains are powered entirely by high-volume, low-margin products that cannibalize core profitability.
Decomposing top-line performance into price, volume, and mix components reveals whether growth is driven by genuine market demand, pricing power, or an unfavorable product mix shift. This clarity helps leadership adjust discount policies, shift marketing investments, or alter sales incentive plans before margins compress.
Conclusion
Variance analysis serves as an ongoing feedback loop that connects operational execution with high-level corporate strategy. When executed with clear materiality boundaries, price-volume-mix decomposition, and structured accountability, monthly reporting turns from a backward-looking administrative chore into forward-looking decision support.
At MyExec, we deliver fractional CFO and FP&A services tailored for growing businesses between $5M and $50M in revenue that are outgrowing founder-led finance. Our flexible, scalable support model gives you access to financial analyst support, senior CFO leadership, or a blend of both based on your complexity and stage.
We have worked across organizations ranging from a few million in revenue to roughly $2B, including nonprofits, private equity-owned firms, closely held businesses, and publicly traded enterprises. Our team has performed sensitivity and scenario analysis that helped client leadership make better decisions and improve cash flow and value over time.
We have helped multiple clients improve enterprise value through disciplined planning, dynamic forecasting, and multi-variable modeling. We have implemented cash flow forecasts and rolling 13-month P&L forecasts, established critical KPI scorecards tracking customer acquisition cost, average revenue per customer, and net revenue retention, and provided advanced margin optimization. Our work includes building integrated three-statement models for new product launches, mergers and acquisitions, capital allocation planning, and business valuations supported by an on-staff Certified Valuation Analyst (CVA).
To see how our team can help you build clear, forward-looking financial systems, explore our fractional FP&A and CFO services today.