The short answer
To prepare your business for sale, close the gaps a buyer will find before the buyer finds them. Start one to three years out with reliable financials, a clear estimate of value, less dependence on you, a healthy spread of customers, and organized records. Begin with the work that takes longest: building the team and the track record.
Most owners of companies with $5M to $50M in revenue sell a business once. The buyer, and the buyer's accountants, attorneys and lenders, have usually done it many times. Preparation is how an owner closes that experience gap. It decides how many buyers take a serious look, how much they offer, and how much of that offer is still there at closing.
This guide covers how to prepare your business for sale one to three years before going to market: what buyers examine, which gaps cost the most, how long each fix usually takes, and the order to do the work in.
How to prepare your business for sale
Buyers review the same handful of areas in every company this size. The table below shows what they look for in each one and how long the fix usually takes when there is a gap. The timelines come from our sell-side and valuation work and assume the owner is also running the business.
| Area | What buyers look for | Typical time to fix a gap |
|---|---|---|
| Financial records | Monthly statements that tie to tax returns and bank statements, with every add-back documented | 6 to 12 months |
| Owner dependence | A business that keeps running, and keeps its customers, when the owner steps away | 12 to 18 months |
| Customers and revenue | No single customer large enough to sink the year, and revenue backed by contracts or repeat orders | 12 to 24 months |
| Team and key people | Managers who run the day to day and have reasons to stay through a sale | 6 to 12 months |
| Growth and the plan | A budget tracked against actuals and a written plan that shows where growth comes from | 6 to 12 months |
| Records and contracts | Leases, licenses, contracts and ownership documents that are current and can transfer | 1 to 6 months |
Two things stand out. The slowest fixes involve people and customers, and they need a track record before a buyer will believe them. A buyer wants to see a second layer of management running the business for a year or more. A single meeting where the owner says it could happen is not enough. That is why the work starts with the slowest items.
Start with your goals and an estimate of value
What you want from the sale and your role afterward
Before fixing anything, get clear on what a good outcome looks like. How much do you need from the sale to fund what comes next? Do you want to sell all of the company or part of it? Do you want to stay on for a year, or hand over the keys at closing? Is there a family member or manager who could be the buyer? Your answers shape everything that follows, including which buyers fit and which gaps matter most.
Why an estimate of value comes before the fixes
An estimate of value tells you where the business stands today and which factors are holding the number down. That turns a long list of possible improvements into a short list ranked by what each one is worth. It also grounds your price expectations early, so a gap between what you hope for and what the market will pay shows up while there is still time to close it. Our guide on how to price your business covers how an estimate of value differs from an asking price.
Timing matters too. Private middle market companies grew earnings 6.9% year over year in the first two months of the third quarter of 2026 (Golub Capital Middle Market Report, Q3 2026). An owner coming off a strong year can start preparation from a good base, and the results of the next two years become the track record a buyer reviews.
Financials a buyer can rely on
Before closing, a buyer's accountants rebuild your profit from your books, tax returns and bank statements. Gaps here are among the most common reasons a price is cut late in a deal. The work is straightforward, though it takes a few clean cycles to show:
- Close the books every month on an accrual basis, within a few weeks of month end, with balance sheet accounts reconciled.
- Make the numbers agree. Your financial statements, tax returns and bank statements should tie out, and your accountant should be able to explain any difference.
- Document every add-back. Personal expenses, one-time costs and above-market family pay can be added back to profit, but only the ones you can prove with invoices or statements.
- Build three years of history on the same basis, so the trend a buyer sees is consistent.
For more detail on what buyers test, see the financials buyers want to see.
Customer concentration and revenue quality
A buyer pays for revenue that stays after closing. When a few customers carry a large share of sales, a buyer sees revenue that could leave the week after the deal closes, and usually responds with a lower price or with part of the price tied to keeping those customers. Revenue with nothing in writing behind it raises the same concern.
Concentration takes the longest to fix, because the answer is winning new customers until the large ones carry less weight. Two years is a realistic window. In the meantime, move key accounts to written agreements, confirm that those agreements can transfer to a new owner, and widen the relationships at your largest customers beyond one contact. Our post on customer concentration explains how buyers measure it.
A team that runs the business without you
Buyers pay for profit that keeps coming after the owner leaves. If you hold the key customer relationships, set pricing and approve most decisions, a buyer has very little to take over. That shows up as a lower price, a longer transition period, or a larger share of the price tied to future results. Our article on owner dependence covers this value driver in depth.
The fix has a clear sequence. Map the decisions and relationships that run through you. Hand off customer relationships one account at a time. Put a second layer of management in place and give it real authority. Write down the core processes. Then give your key people reasons to stay through a sale, such as retention or incentive plans, set up with your attorney and CPA. A buyer will want to see this team running the business for at least a year.
Records, contracts and systems
Before closing, a buyer's attorneys review every contract, lease, license and corporate record. Missing documents, leases that cannot transfer, and open disputes slow a deal down or change its price. This is the fastest area to fix, and it is work for your attorney. Ask them to review:
- Customer and supplier contracts, and whether each one needs consent to transfer
- Real estate leases, licenses and permits
- Ownership records, corporate minutes and any agreements among owners
- Intellectual property, including trademarks, software and customer data
- Employee agreements covering confidentiality and non-solicitation
Then put the documents in one organized place. The data room a buyer will eventually use is much easier to build when the records already live in one folder.
Margins and working capital
Buyers look closely at gross margin by product or service line and at how margins have moved over time. A falling margin reads as risk, even when revenue is growing. Know your margin by line of business and be ready to explain any decline.
Working capital also needs attention well before a sale. Most deals set a target level of working capital the business must deliver at closing, and the price adjusts up or down from there. Owners who understand their normal working capital, and how it moves through the year, negotiate that target from a position of strength. Our guide to working capital in a business sale walks through how the target changes what you take home.
A one to three year readiness plan
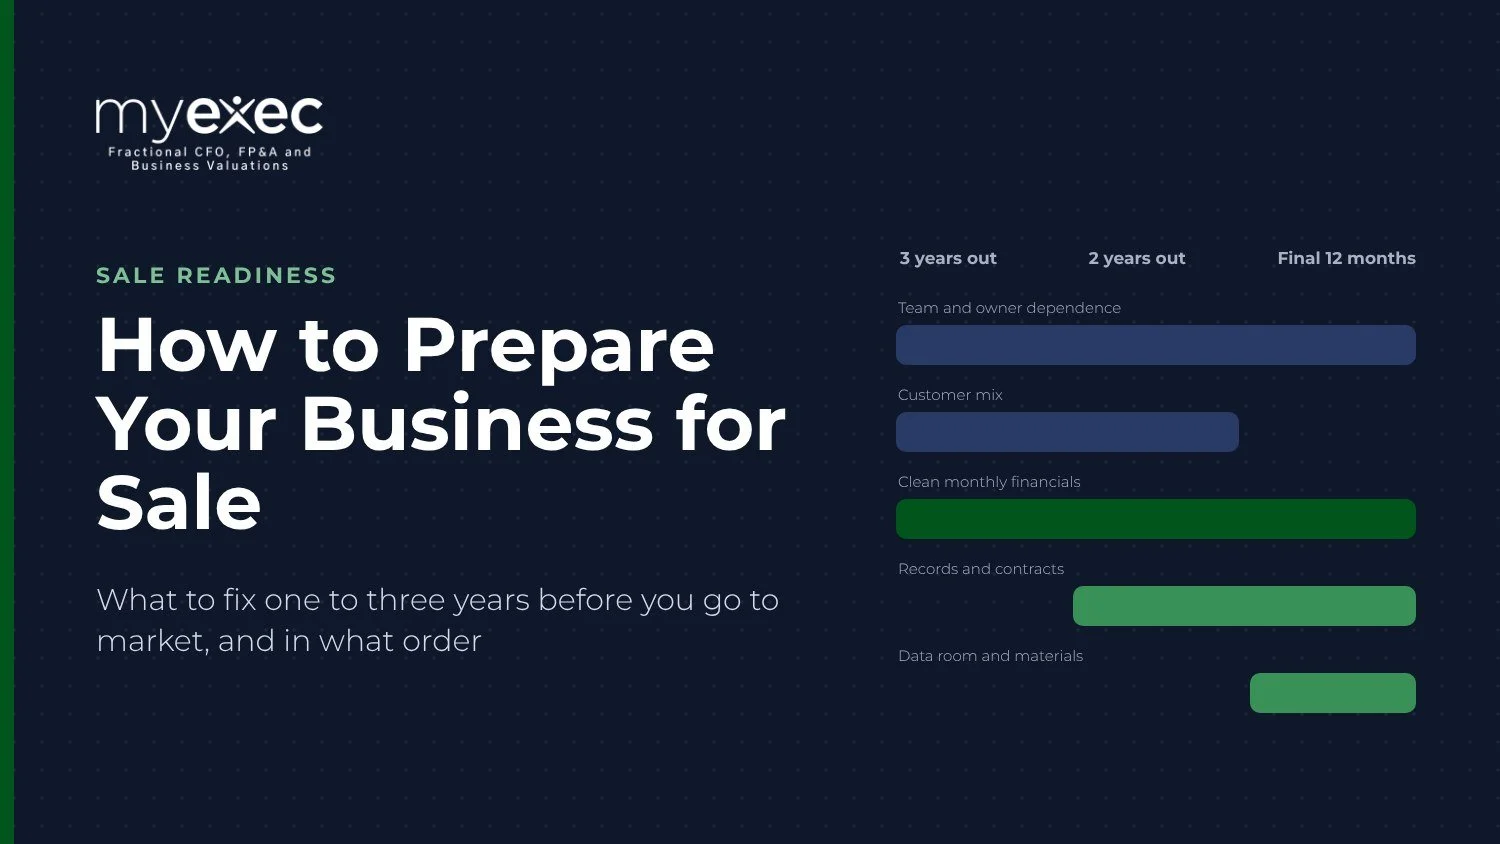
The chart below puts the work in order. Start the slow items first and the fast ones last, so each one is finished, and has a track record behind it, when buyers arrive.
Three years out. Get an estimate of value and set your goals. Start the slowest work: building the management team, handing off relationships, and widening the customer base. Move the books to a monthly close if they are not there already.
Two years out. Keep building the track record. Have your attorney review contracts, leases, licenses and corporate records, and fix what needs fixing. Put retention plans in place for key people. Track a budget against actuals every month.
The final 12 months. Refresh the estimate of value. Organize the records into a data room. Prepare the marketing materials with your advisor. Keep running the business well, because the most recent results are the ones a buyer looks at hardest.
What preparation can be worth: a worked example
The example below is hypothetical. The numbers are made up to show how buyers react to risk, and they are not market data. Real multiples depend on the industry, the company's size, the buyer and the market at the time of the sale.
Picture a services company with $12M in revenue and $1.5M of adjusted EBITDA. The owner holds the three largest accounts, those three customers bring in 45% of revenue, and the books are kept in-house and reconciled once a quarter. A buyer likes the business but sees risk in all three areas. The buyer responds the way buyers usually do: a more cautious multiple, and a larger share of the price paid later through an earnout tied to keeping those customers.
Now picture the same company after two years of preparation, with profit unchanged so only the readiness work differs. A sales leader owns the large accounts. New customers have brought the top three down to 25% of revenue. A CPA reviews monthly statements, and every add-back is documented.
| Hypothetical | Today | After two years of preparation |
|---|---|---|
| Adjusted EBITDA | $1.5M | $1.5M |
| Multiple a buyer offers | 4.5x | 5.5x |
| Headline price | $6.75M | $8.25M |
| Share tied to an earnout | 25% | 10% |
| Cash at closing | About $5.1M | About $7.4M |
The larger gain in this example is the cash at closing. Earnouts depend on targets the owner no longer fully controls after the sale. A business that shows less risk gives the buyer less reason to hold part of the price back. The higher multiple reflects the same lower risk: a buyer pays more for profit that is easier to verify and more likely to continue.
Who should be on your preparation team
Preparing a business for sale is team work, and each advisor covers a different part of it. The best results come when they work from the same plan and the same numbers.
| Advisor | What they cover in preparation |
|---|---|
| CPA | Financial statements, tax returns, and how the sale should be structured for tax |
| Attorney | Contracts, leases, corporate records, employee agreements, and later the deal documents |
| Wealth or financial advisor | What you need from the sale to fund what comes next, and planning for the proceeds |
| Valuation and finance lead | The estimate of value, the readiness plan, monthly reporting, and the numbers a buyer will test |
| M&A advisor | The buyer market, timing, marketing materials, and running the sale process when you are ready |
Bring your CPA and attorney in early, well before an offer arrives. Many owners already have strong relationships with both. The valuation and finance work sits between them: it turns the company's numbers into the story a buyer will test, and it gives every advisor the same starting point. At MyExec, our valuation professionals and finance team fill that role and work alongside the owner's existing advisors.
Common mistakes owners make when preparing to sell
The same handful of mistakes comes up again and again. Each one is avoidable with enough lead time.
- Waiting for an offer to start. An unsolicited offer sets the timeline on the buyer's terms. Owners who start early choose when to go to market.
- Fixing the fast things first. Cleaning up records feels productive, but the slow items, such as the team and the customer mix, are the ones that need a track record.
- Stretching the add-backs. Every add-back a buyer rejects lowers the profit the price is built on, and it makes the buyer question the rest of the numbers.
- Going to market without knowing your number. Without an estimate of value, owners either anchor too high and lose buyers, or accept too little.
- Letting results slip during the sale. A sale takes months, and the most recent quarters get the closest look. Keep the business running at full speed.
- Telling too many people too early. Word of a sale can unsettle employees, customers and suppliers. Keep the circle small until the timing is right, and plan how and when to tell key people.
- Working with advisors one at a time. When the CPA, attorney and finance lead each work from different numbers, the gaps show up in diligence. One plan and one set of numbers prevents that.
How to check your sale readiness today
Answer these eight questions honestly. Each "no" is a gap a buyer is likely to find.
Quick self-check
0 of 8 checked. Check the statements that are true today.
For a fuller picture, our free Sale Readiness Assessment scores the six areas a buyer reviews in about five minutes and emails you a prep plan.
Frequently asked questions
How far in advance should I start preparing my business for sale?
Start one to three years before you plan to go to market. The fastest fixes, such as cleaning up contracts and records, take a few months. The slowest, such as building a management team and reducing customer concentration, need a year or more of results before a buyer will give them full credit. Starting early gives you the most choices on timing.
What should I fix first before selling my business?
Fix the slowest items first: owner dependence, management depth and customer concentration. They need a track record, so they take the longest to show up in value. At the same time, move your books to a reliable monthly close, because every later step depends on numbers a buyer can trust. Records and contracts can come later.
Do I need audited financial statements to sell my business?
Not always. Many companies of this size sell with reviewed or well-prepared statements, and the buyer commissions its own quality of earnings review. What matters most is that your statements are accurate, prepared consistently and tied to your tax returns. Whether an audit or review is worth it depends on your likely buyers and lenders, so discuss it with your CPA.
How do I make my business less dependent on me before a sale?
List the decisions and relationships that run through you, then hand them off one at a time. Put a second layer of management in place with real authority, write down the core processes, and introduce your team to key customers and suppliers. Buyers will want to see the business running this way for at least a year before a sale.
Should I get a valuation before I prepare the business for sale?
Yes. An estimate of value shows where the business stands today and which factors hold the number down, so you can rank the fixes by what each one is worth. It also grounds your expectations early. A formal valuation from our valuation professionals can follow later, as the baseline for every decision in the sale.
Start your readiness plan with MyExec
The earlier you know where your business stands, the more of the gaps you can close before a buyer sees them. Our free Sale Readiness Assessment takes about five minutes, needs no financials, and gives you a readiness score, the deal risks a buyer would find, and a prep plan by email.
Prefer to read more first? See how we approach selling your business.